A loan EMI is easy to agree to and hard to shrink. Because it is fixed, the share of your income it takes matters more than the amount itself.
The ratio
Divide your total monthly EMIs and other loan repayments by your monthly income. If you pay ₹28,000 in EMIs and earn ₹90,000, the ratio is about 31%.
How lenders see it
When you apply for a loan, lenders usually check how much of your income is already committed to repayments. Many people choose to keep that share well below half of income so that there is room for essentials and savings. Your own comfortable level depends on your costs and how stable your income is.
Count everything
- Home, car and personal loan EMIs.
- Education loan repayments.
- Credit card minimums if you carry a balance.
- Buy-now-pay-later instalments.
Measure it from your real transactions
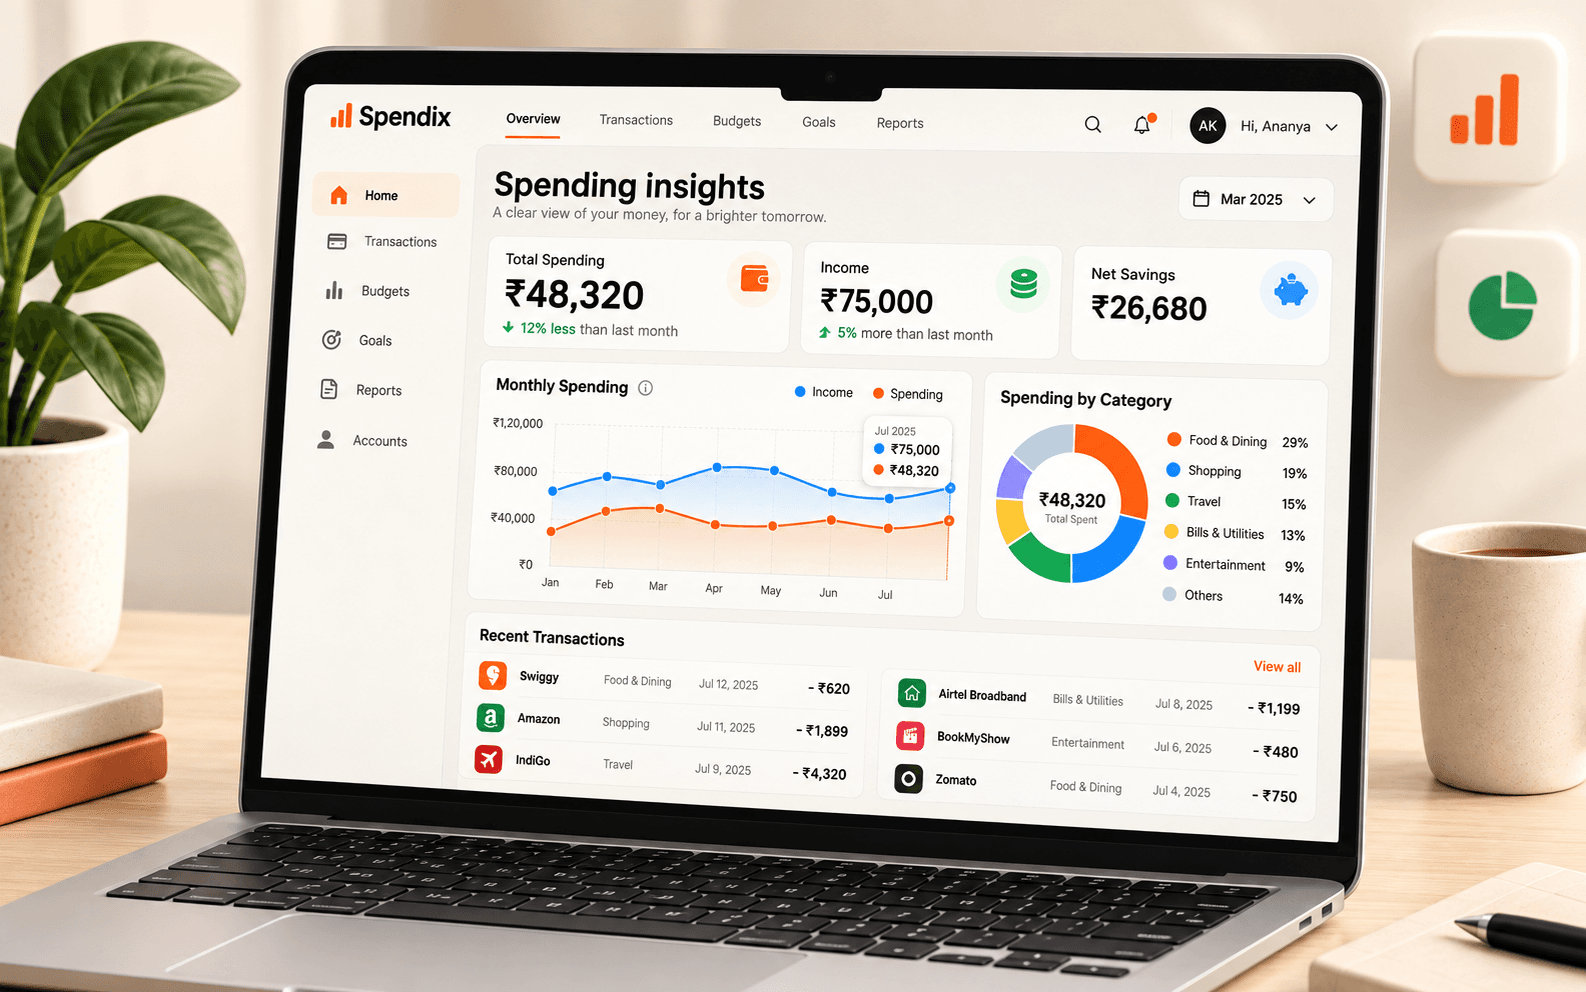
The EMI and loan burden report in the Report library finds repayments by category or by EMI in the merchant name, then shows what you paid each month and what share of that month’s income it was. Categorise your repayments under a loan or EMI category so none are missed.
If the ratio is high
- List every loan with its rate and remaining term.
- Check whether the costliest loan can be prepaid or refinanced.
- Hold off on new borrowing until the ratio comes down.
- Raise income, or reduce other costs, to create room.
A clearer story in every report.
Explore totals, trends, and account activity in reports you can actually use.