Salaried budgeting assumes the same amount arrives every month. Freelancers and consultants get lumpy income: a great month, then a thin one. The solution is to budget from an average and build a cushion, not from your best month.
Step 1: Know your real monthly income
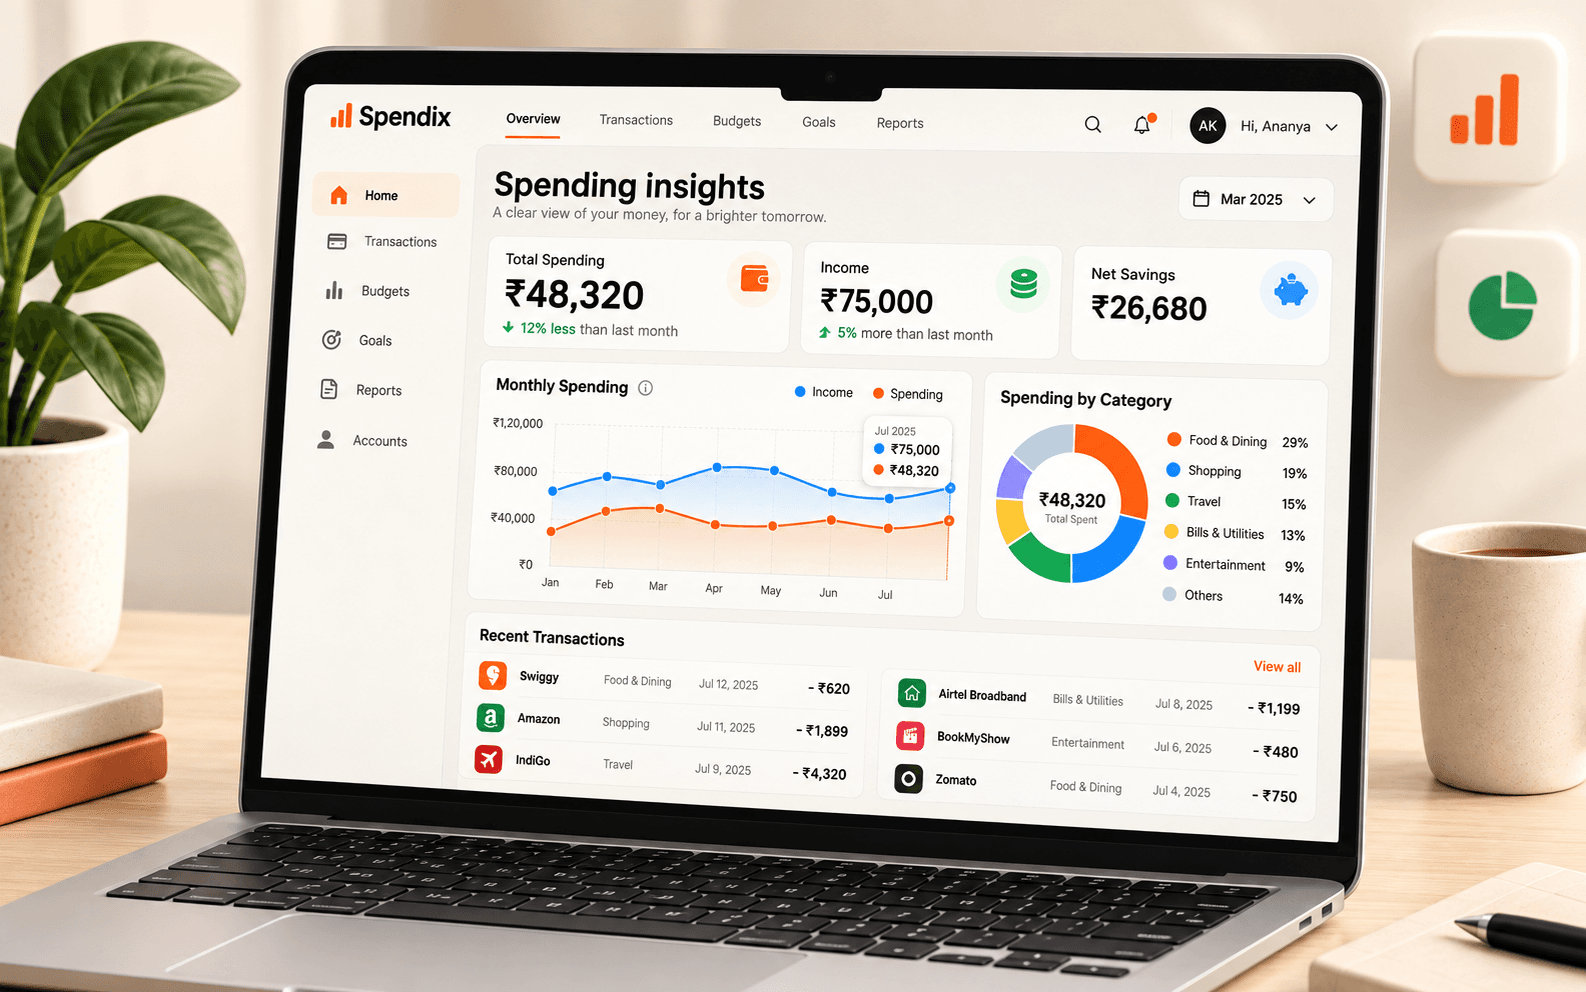
Add up what you received over the last six to twelve months and divide by the number of months. That average, not the best month, is your planning figure. The Net cash flow report shows income and spending month by month so you can see the swings.
Step 2: Find your baseline
Your baseline is the amount you must spend every month: rent, EMIs, utilities, food, insurance. Add it up once. Your aim is for the average income to cover it comfortably.
Step 3: Pay yourself a steady amount
Rather than spending whatever arrives, move a fixed amount into your personal account each month and leave the rest in a buffer. In a good month the buffer grows. In a thin month it covers the gap.
Step 4: Set money aside for tax
Income that has not had tax taken off needs money kept aside for it. Ask your CA what share to set aside and keep it somewhere separate, so it is not mistaken for spending money.
Step 5: Keep business and personal apart
Mark each transaction as business or personal. The Business vs personal report then shows what the business really costs, and your CA gets a clean record.
Review monthly
- Record the month’s income and expenses.
- Compare your average income with your baseline.
- Top up the buffer if you can, and note how many months it would cover.
A clearer story in every report.
Explore totals, trends, and account activity in reports you can actually use.